The short answer
Most homeowners policies cover window glass broken suddenly by a covered event, like a break-in, vandalism, a storm or a falling branch, after you pay your deductible. They generally do not cover foggy dual pane glass, failed seals or old, worn out windows. Because a single pane repair often costs less than a typical deductible, get a written estimate before you file.
We get this question on almost every break-in call, usually while someone is standing in their living room looking at glass on the carpet. The honest answer is "it depends on why it broke and what your deductible is." Here is how it usually shakes out.
Every policy is different and we are a glass company, not an insurance agent. Use this to know what to ask, then confirm with your agent or your policy.
What is usually covered
Homeowners policies are built around sudden, accidental damage from what the policy calls covered perils. For windows, that typically includes:
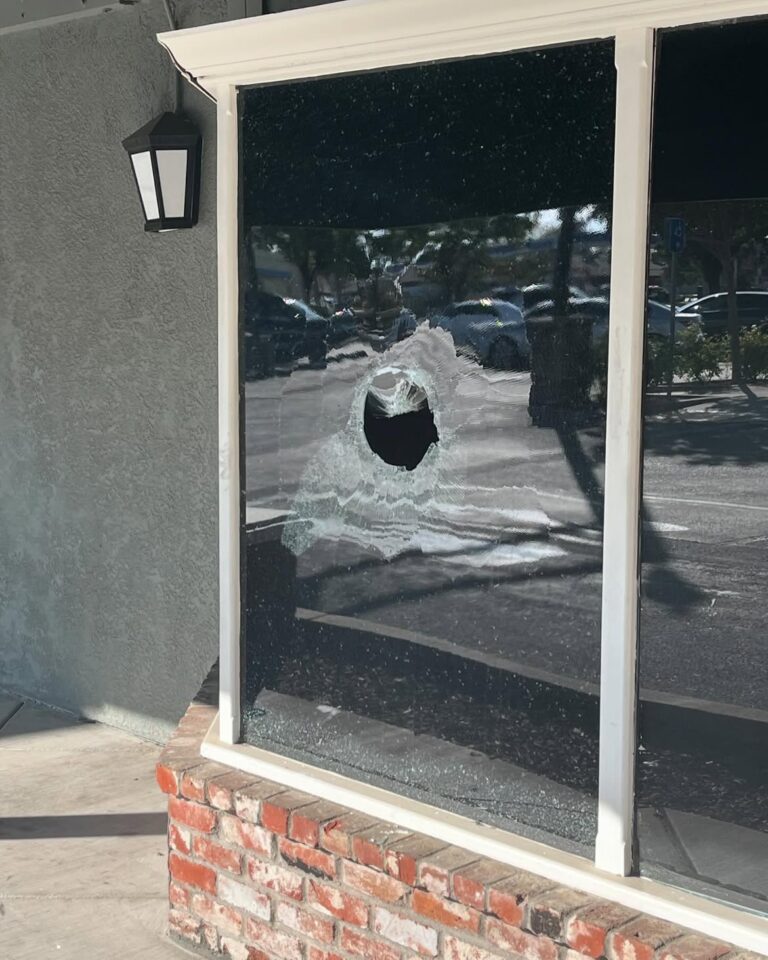
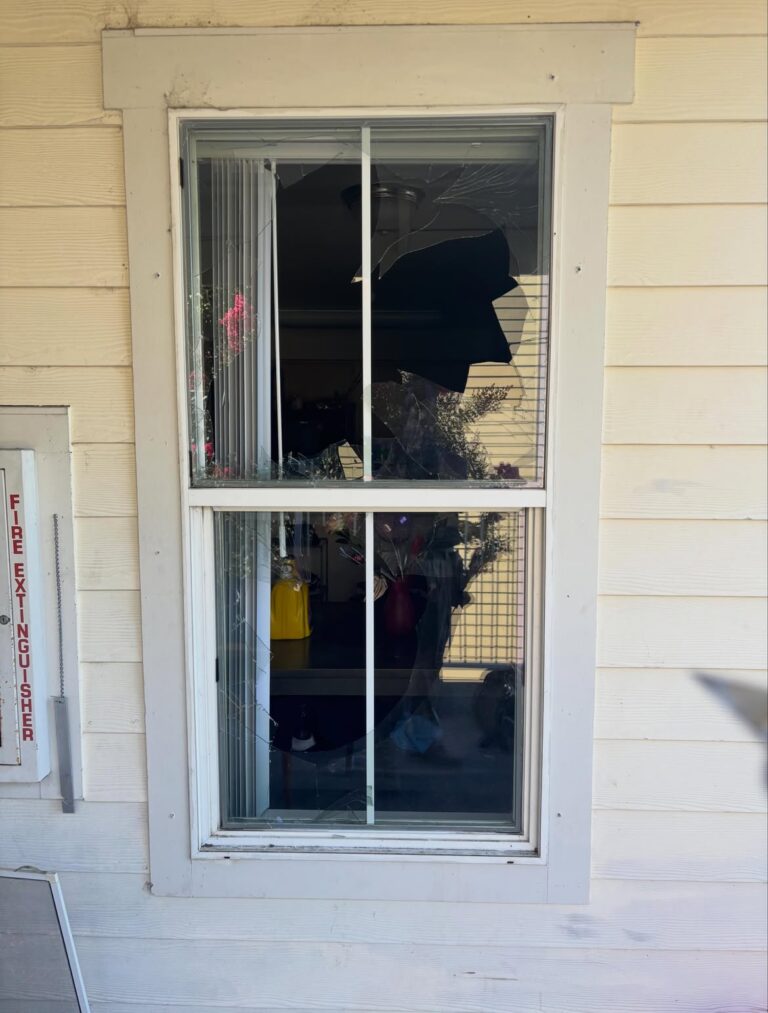
- Break-ins and attempted break-ins. The broken glass and often the damaged frame or door are part of the claim, along with anything stolen.
- Vandalism. A rock through the front window, a smashed slider. One catch: many policies stop covering vandalism if the home has been sitting vacant for an extended period, often 60 days.
- Storms and wind. Wind-driven debris or a limb coming down on the house.
- Falling objects and fire.
What is usually not covered
- Foggy or cloudy dual pane windows. A failed seal is age and wear, not sudden damage. Insurers treat it as maintenance. The fix is replacing the sealed glass unit, which we explain in why are my windows foggy between the panes.
- Gradual deterioration. Rotted wood sashes, corroded aluminum frames, sashes that will not stay up.
- Cracks that grew over time. A crack that started as a chip and spread with the summer heat is hard to tie to a single event.
- Poor installation. Leaks and failures caused by how a window was installed usually go back to the installer or the window warranty.
Sudden damage is an insurance question. Fog, drafts and old frames are a maintenance question.
Do the deductible math first
This is where a lot of claims fall apart. Many policies now carry deductibles of $1,000 or more. If replacing one broken pane costs less than your deductible, the insurer pays nothing, but the claim can still end up on your claims history, which insurers look at when they price your renewal.
So before you call your insurance company, get a written estimate for the glass. If the repair is well under your deductible, most people simply pay for it. If the damage is bigger, like a slider, several windows or a break-in with other losses, filing usually makes more sense.
We measure on site and give you an itemized price in writing, plus photos, so you can decide whether a claim is worth it.
When someone else broke it
If a neighbor's kid sent a baseball through your window, or a landscaper's mower threw a rock into your slider, the person or business responsible may be the one who pays, through their own homeowners or business liability coverage. Get their contact information, take photos and keep the estimate. Many neighbors would rather just pay for the glass directly.
Renters and landlords
If you rent, the building itself, including the window glass, is generally the landlord's responsibility to repair. California's habitability law lists unbroken windows and doors as part of keeping a rental weatherproof. If the tenant or a guest caused the damage, the landlord may pass the cost along. Renters insurance mainly protects your belongings, not the building. Property managers can read our guide for Sacramento rentals and apartments.
What to document before anything gets cleaned up
- Wide photos of the window from inside and outside, then close ups of the damage
- Photos of anything on the floor and any damage to the frame, blinds or flooring
- A police report number for any break-in or vandalism
- The date and time you found it
- A written, itemized estimate that lists the glass type, such as tempered, Low-E or dual pane
- Receipts for any board up or temporary repairs
Most policies expect you to take reasonable steps to keep the damage from getting worse, like covering an open window. The cost of a board up is often part of the claim, so keep the invoice. If you need help with that first hour, see what to do after a window breaks.
Quick answers
Will filing a claim for a broken window raise my insurance rates?
It can. Insurers look at your claims history when they price a renewal, which is why small claims under or near your deductible are often not worth filing. Ask your agent how your company handles it.
Does homeowners insurance cover foggy windows?
Usually not. Fog between the panes means the seal has failed with age, which insurers treat as wear and tear. The repair is replacing the sealed glass unit, often without replacing the frame.
Should I fix the window before the adjuster comes out?
Secure it, yes. Cover the opening so rain, heat and intruders stay out. Document everything with photos first and keep receipts. Hold off on the permanent glass replacement until you know how your insurer wants to proceed.
Does car insurance or renters insurance cover a house window?
Renters insurance mainly covers your belongings, and car insurance covers your car. The house window is usually the homeowner or landlord policy, or the person who caused the damage.